Hinge Health is seeing early traction with its migraine and gastrointestinal care programs as it pushes beyond musculoskeletal care and builds a broader, multi-condition platform.
But the company’s core MSK business remains the engine fueling its robust growth.
“Our vision has always been to automate the delivery of care using technology to close the gap between the care people need and the care they actually receive. We’re now applying that same approach and the same trusted relationships with employers and partners in neurology and gastrointestinal care,” Daniel Perez, Hinge Health co-founder and CEO, told analysts and investors on the third-quarter earnings call Monday. “We’re not starting from scratch in each new category. We’re extending a platform that’s already proven into conditions that are often connected to the ones we already treat. We believe that’s a fundamentally different and more powerful way to expand than what other companies in our space are attempting.”
During a Q&A with analysts and investors on the earnings call, Perez asserted, “We’re not taking our eye off the ball in MSK. I think we’re actually widening our lead on MSK… But it’s allowing us to expand into other areas as well.”
In the third quarter, the company posted $235 million in revenue, up 52% from $154 million a year ago, and above its guidance range of $223 million to $225 million. The company posted third-quarter adjusted earnings of 66 cents per share, exceeding Wall Street analysts’ estimates of 60 cents per share. Hinge Health’s non-GAAP income from operations increased 154% to $77.2 million in the third quarter.
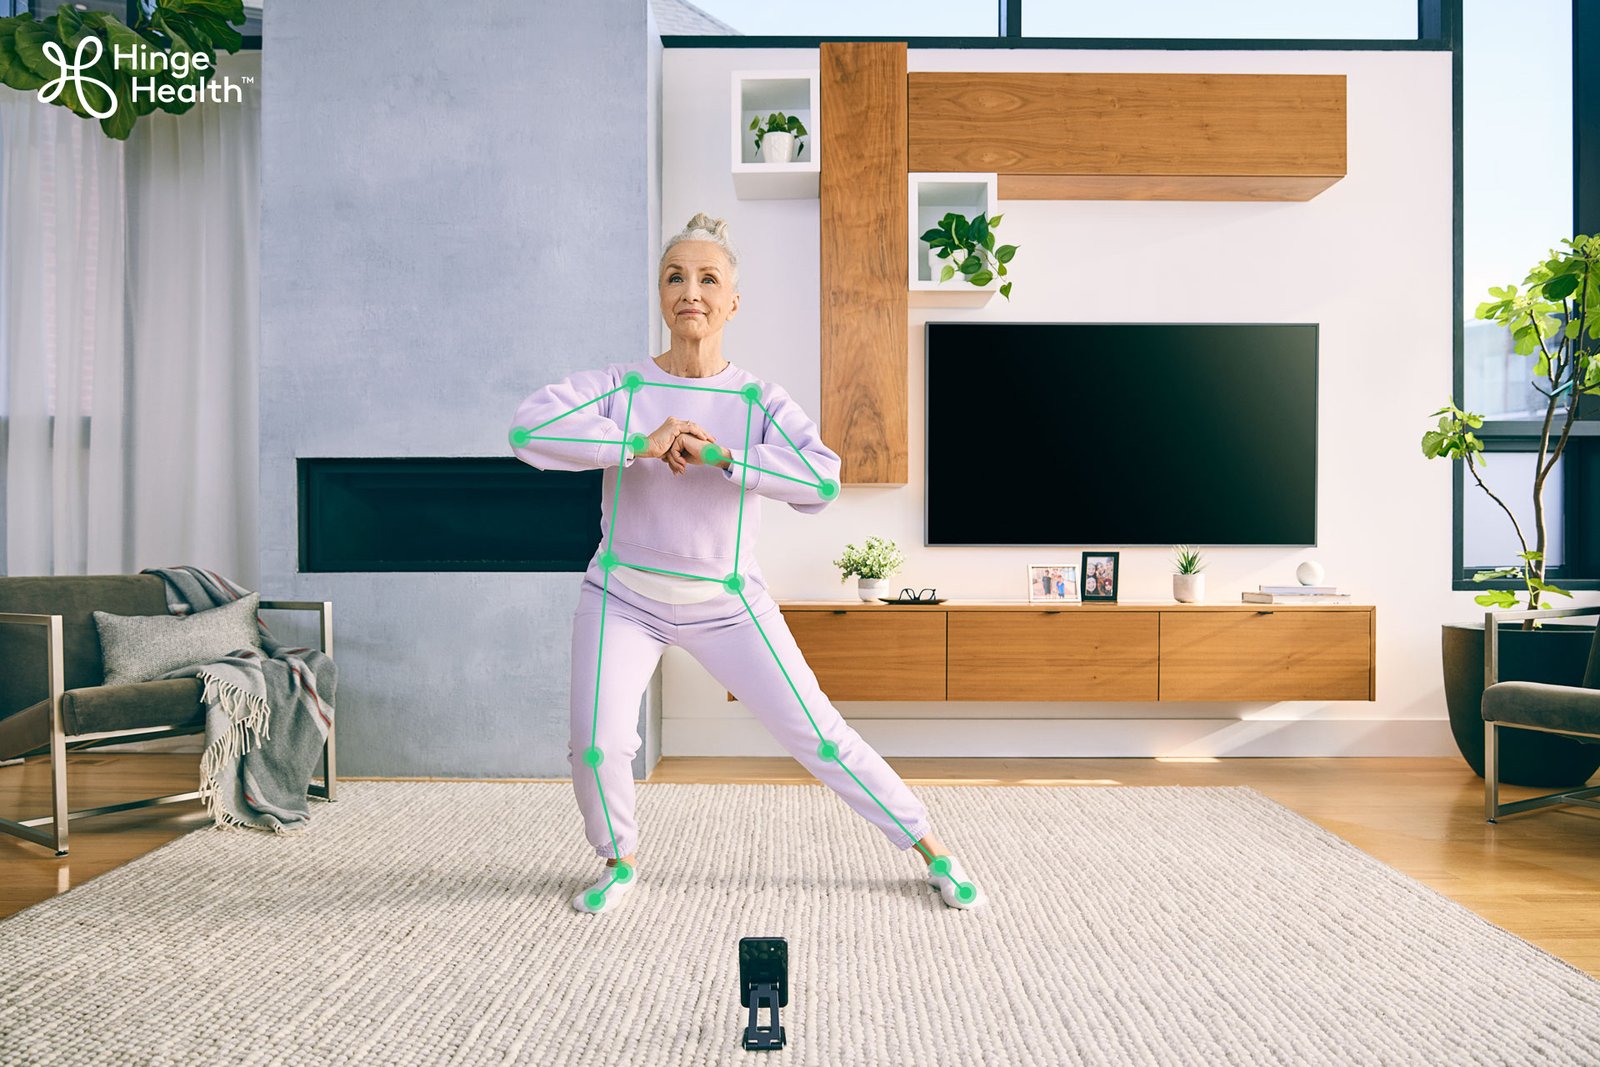
Hinge Health, which launched in late 2014 and went public in May 2025, developed software combined with AI to automate physical therapy services for joint and muscle health. The company has designed its platform to address a broad spectrum of MSK care, including acute injury, chronic pain and post-surgical rehabilitation. To address the automation of care, Hinge has developed AI-powered motion tracking technology, a proprietary FDA-cleared wearable device called Enso and an AI-supported care team to deliver scalable and personalized MSK care.
The company reported strong client growth, with 3,270 clients as of September 30, up 28% from a year ago. Last twelve months (LTM) calculated billings increased 54% year-over-year to $960 million as of September 30, compared to $624 million during Q3 2025.
The company also benefited from strong operational efficiency as it reported gross margin of 87% in Q3, compared to 82% during the same quarter a year ago.
Free cash flow for the quarter was $113 million, representing a 51% free cash flow margin. The company ended the September quarter with total cash and equivalents of $359 million.
Based on strong Q3 and year-to-date results, Hinge Health boosted its 2026 outlook, now expecting full-year revenue to reach between $879 million and $881 million, reflecting year-over-year growth of 50% at the midpoint. That compares to the prior revenue target of $856 million to $860 million. The company now projects non-GAAP income from operations to be between $266 million and $268 million, reflecting year-over-year growth of 123% and non-GAAP operating margin of 30% at the midpoint.
Core MSK is still the company’s largest revenue contributor by a wide margin, Perez noted, and that business is growing robustly. “We expect it to remain that way for years to come; the opportunity at MSK remains massively underpenetrated,” Perez said.
“The MSK opportunity is still enormous. Musculoskeletal conditions are among the leading drivers of disability and healthcare spend in the United States, and the vast majority of people in America still don’t have access to a digital MSK solution,” Perez said during the call.
“We built something that works clinically, commercially, and economically, and we’re still in the early innings of penetrating that market. We are the undisputed leader in this space, and we estimate 88% of lives within our markets are yet to be won, leaving a long runway for growth. That alone is a multi-year growth opportunity,” he said.
The company is building on top of that MSK care foundation as it expands into migraine care and gastrointestinal care. Hinge acquired GI startup Cylinder Health in August for $105 million in cash.
The company’s client base is up almost 30% year-over-year for its MSK care program and roughly 40% for its new GI Care Program since the acquisition announcement of Cylinder Health in August, Perez noted.
The company expects to make more acquisitions and is even looking at hardware acquisitions, Perez said. “I think too many technology companies, especially in healthcare, focus exclusively on software, but I absolutely firmly believe you will not automate care delivery without also investing in hardware. And, we’ve shown we’re pretty good at hardware,” he said, as the company internally developed its Enso wearable device.
Perez told Bloomberg last month that the company was interested in hardware that can augment virtual care.
“We will build organically first and use M&A when it accelerates our timeline. And our acquisitions, particularly in hardware, have historically been small tuck-ins of technology in a team, and then you build it out into something much larger,” he added.
Looking at the company’s new care programs, Perez called out notable early results from Hinge’s migraine program, which is still in early access: 23% reduction in monthly migraine days, 28% reduction in migraine duration, equivalent to roughly five hours and just over half of surveyed members achieved a clinically meaningful improvement.
“We’re also seeing a meaningful reduction in monthly prescription use days, which matters both for members and for the clients paying for their care,” Perez said.
More than 800 clients, representing 9 million lives, now have access to the migraine program, approximately double the previous quarter, according to management. The migraine program was announced in May.
For the GI care business, Hinge Health is taking Cylinder’s existing program and building it into the same app and care infrastructure it uses for MSK and migraine. The company is targeting summer 2027 for the fully integrated product. Meaningful revenue contribution should emerge particularly in 2028, after Hinge gets a fuller sales cycle with the integrated product, Perez noted.
Hinge Health sees an opportunity to offer health plans and employers one integrated care platform that covers multiple health conditions rather than separate point solutions.
Nearly one in two people with GI conditions also have MSK pain, and 70% of people with
migraine also have a GI condition, Perez noted.
“GI cost has been a growing pain point for employers and health plans, especially with the growth of GLP-1s, given GI side effects are so common, and our employer clients are very grateful for taking this on,” he said during the call.
Hinge Health had a strong selling season in Q3, according to Aaryn Pure, Hinge Health’s chief commercial officer, with three new Fortune 15 clients. “We’ve already received verbal agreements on more lives this year than we closed in all of last year, and last year was a record-breaking sales year for adding eligible lives,” Pure noted.
More than 10 million lives across more than 800 clients have access to multiple Hinge products, he said.
Small and midsize businesses are becoming an important growth channel for the company, even though Hinge began investing in that market just a year ago. Through Q3, Hinge Health closed nearly 1 million SMB lives, “demonstrating we’re not just winning at the top of the market, we’re adding clients across every size tier,” Pure said on the call.
He also noted that some health plan and third-party administrator (TPA) partners are implementing or considering arrangements where Hinge Health is automatically embedded or offered on an opt-out basis in their SMB book of business.
“Being the first-mover preferred partner is allowing us to capture that market,” Pure said.
The company also announced Monday that Jim Pursley will step down as president, effective January 1, and will join Hinge Health’s board of directors. Following this transition, Pure will lead the commercial organization, the company said.
In an analyst note, Ryan Daniels, group head of healthcare technology and services at William Blair, wrote that Hinge Health demonstrates “market leadership with significant advantages both on the product and go-to-market fronts.”
“With a nearly 150% increase in shares YTD, HNGE now trades at approximately 11 times our 2027 adjusted gross profit, a premium to mature, high-margin, growth-oriented healthcare IT peers. Still, at these levels, we believe the stock presents a compelling long-term risk/reward and see continued growth momentum and upside to operating income and free cash flow estimates,” Daniels wrote.